
When you're trying to figure out which health insurance plan is right for you, you're usually buried in a mountain of details: deductibles, copays, provider networks, and more. It can feel impossible to compare them apples-to-apples.
This is where actuarial value (AV) comes in. Think of it as a plan’s "generosity score."
In simple terms, actuarial value tells you what percentage of medical costs a health plan expects to pay for the average person over a year. The rest is what you’ll cover out-of-pocket.
What Is Actuarial Value and Why Should I Care?
Actuarial value is one of the most powerful tools you have for cutting through the noise. It gives you a single, standardized number to understand a plan's financial value. It’s not about the quality of doctors or hospitals, but purely about how much of the bill the insurance company picks up versus how much you do.
Let's use an analogy. Imagine a plan has an actuarial value of 80%. This means that, on average, the insurer expects to pay 80% of all covered medical bills for its members. You, the member, would be responsible for the other 20% through your deductible, copayments, and coinsurance.
This concept is the backbone of the Affordable Care Act (ACA) marketplace plans.
The Foundation of ACA Metal Tiers
The ACA marketplace neatly categorizes plans into "metal tiers" – Bronze, Silver, Gold, and Platinum. These aren't just clever names; they're directly tied to actuarial value. This system was created to make it much easier for everyone to quickly grasp how much a plan will help with costs.
Here's how they break down:
- Bronze plans have an AV of around 60%
- Silver plans hit the 70% mark
- Gold plans are set at 80%
- Platinum plans offer the highest value at 90%
This cost-sharing percentage applies to a specific list of services. You can learn more about what services are covered in our guide to the ten essential health benefits. You can also find more detailed definitions of actuarial value standards at actuarialstandardsboard.org.
It’s crucial to remember that AV is an average calculated across thousands of people. It’s not a guarantee of your exact costs. But it gives you a fantastic starting point for understanding how much financial protection a plan really offers.
Decoding the ACA Metal Tiers: From Bronze to Platinum
If you’ve ever shopped on the Affordable Care Act (ACA) marketplace, you’ve seen the "metal tiers": Bronze, Silver, Gold, and Platinum. This system is designed to make comparing health plans a bit easier, giving you a quick sense of how costs will be split between you and your insurance company.
Think of each tier as a different cost-sharing agreement. It tells you, on average, what percentage of your medical bills the plan will cover for a standard population. Getting a handle on these levels is the first step to finding a plan that fits both your budget and your healthcare needs.
This simple chart shows how it all connects.
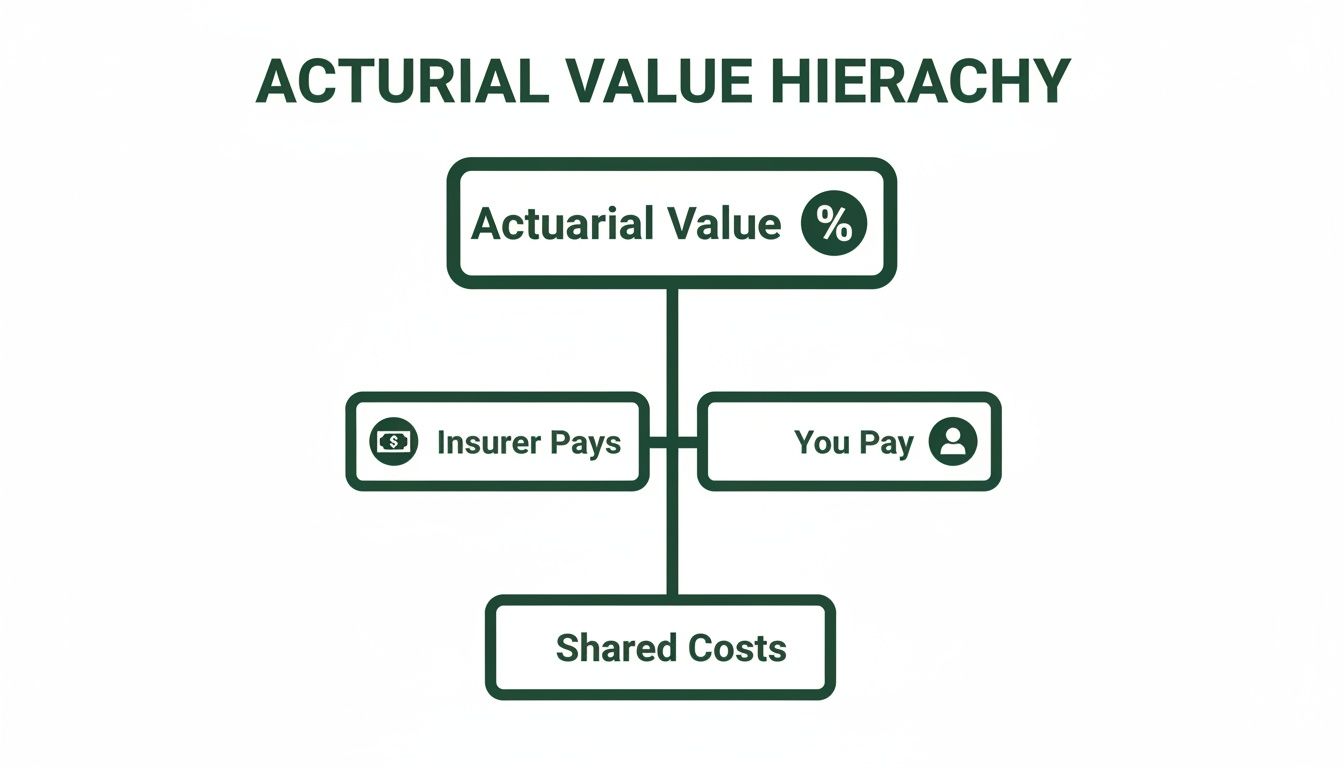
As you can see, when a plan's actuarial value goes up, the insurer pays a bigger slice of the pie, and your expected share gets smaller.
Understanding Each Metal Level
The tiers work on a classic trade-off: your monthly premium versus what you pay when you actually get care. Typically, plans with lower monthly payments come with higher out-of-pocket costs, and the reverse is true for plans with higher premiums.
Here’s exactly how that breaks down for each tier:
- Bronze Plans (60% AV): The insurer pays about 60% of your covered costs, leaving you with 40%. These plans offer the lowest monthly premiums but demand the most from your wallet when you see a doctor, with high deductibles and copays.
- Silver Plans (70% AV): Here, the split is closer to 70/30. Silver plans are often called the "middle-of-the-road" option, striking a balance between monthly costs and out-of-pocket expenses.
- Gold Plans (80% AV): With an 80/20 split, Gold plans mean you'll pay more each month. The payoff comes in the form of much lower costs when you need medical care.
- Platinum Plans (90% AV): The insurer covers a whopping 90% of the bills, while you’re responsible for just 10%. These plans have the highest monthly premiums but offer the most predictable, lowest costs when you use your insurance.
For a deeper look at weighing these different factors, our guide on how to compare health insurance plans walks you through the practical steps of looking beyond just the metal.
A Real-World Scenario
Let's make this tangible. Imagine you need a minor surgery that costs $10,000 in covered medical expenses.
With a Bronze plan (60% AV), you'd be looking at a bill of around $4,000, while your insurer pays the other $6,000. On the other hand, if you had a Platinum plan (90% AV), your share shrinks to just $1,000, with the insurer covering the remaining $9,000.
This example cuts right to the heart of the decision. A Bronze plan saves you money every month, but a Platinum plan provides a much stronger safety net if you end up needing significant medical attention.
Here's a crucial point many people miss: actuarial value is an average calculated across a huge group of people. Your actual, personal costs will ultimately depend on your own healthcare needs, the plan's specific deductible, and its copay structure.
The Silver Plan Secret: Cost-Sharing Reductions
Silver plans have a unique feature that can be a game-changer for people who meet certain income qualifications: Cost-Sharing Reductions (CSRs). These are extra government subsidies that directly lower the amount you pay for deductibles, coinsurance, and copayments.
A CSR essentially gives a Silver plan a major upgrade. It boosts the actuarial value without increasing the premium you pay. For those who qualify, a standard 70% AV Silver plan can be supercharged to act like a plan with an 87% or even 94% AV.
This means you could get the low out-of-pocket protection of a Gold or Platinum plan while still paying the lower monthly premium of a Silver plan. It’s truly a hidden gem on the marketplace.
How Actuarial Value Impacts Your Total Healthcare Spending
So, what does all this talk about actuarial value actually mean for your wallet? This is where the rubber meets the road. The AV of a plan creates a direct trade-off between what you pay every month (your premium) and what you pay when you actually go to the doctor.
It’s a straightforward seesaw relationship. Plans with a low actuarial value, like a Bronze plan, come with lower monthly premiums. The catch? You’ll face higher out-of-pocket costs when you need care. On the other end, plans with a high actuarial value, like Gold or Platinum, have steeper monthly premiums but ask you to pay much less when you see a doctor or need a procedure.
Think of it as choosing how you want to pay for your healthcare: a little bit every month in predictable payments, or potentially a lot all at once when you get sick.
A Tale of Two Families
Let's make this real by looking at two families navigating this exact choice.
The Millers Go for a Bronze Plan (60% AV)
The Millers are young, healthy, and watching their budget closely. They pick a Bronze plan with an attractive, low $500 monthly premium. For months, it feels like the perfect decision—they’re saving a ton of money.
Then, their son has an accident and breaks his arm. An ER visit, X-rays, and a cast later, the total bill comes to $6,000. Because their plan has a high deductible, they find themselves on the hook for the first $5,000 of that bill. That one unexpected event puts a massive, immediate dent in their finances.
The Chens Pick a Gold Plan (80% AV)
The Chens expect to use their insurance more often and value predictability over low monthly costs. They select a Gold plan with a $1,200 monthly premium. It’s a bigger hit to their budget each month compared to the Millers.
When their daughter has a similar medical event that also costs $6,000, their financial experience is completely different. Their plan’s deductible is just $1,000. After meeting that, their 20% coinsurance applies to the remaining $5,000, meaning they owe another $1,000. Their total bill for the incident is $2,000—a manageable amount, and less than half of what the Millers had to pay.
Visualizing the Financial Trade-Off
These stories bring the core concept of what is actuarial value in health insurance to life. It’s a fundamental choice you have to make.
- Low-AV Plans: You pay less month-to-month, but you’re accepting more financial risk. A serious illness or injury could mean you’re paying thousands out of pocket before your insurance really starts to help, possibly all the way up to your out-of-pocket maximum.
- High-AV Plans: You pay a higher premium for peace of mind. Your costs for care are far more predictable, and a medical emergency is much less likely to become a financial catastrophe.
The right choice boils down to your personal risk tolerance, health needs, and financial situation. Would you rather pay more in guaranteed premiums for a solid safety net, or pay less monthly and save that money for medical bills that might—or might not—come?
There’s no one-size-fits-all answer here. A healthy person could save a lot of money over the years with a Bronze plan. But for a family managing chronic conditions, the financial stability of a Gold or Platinum plan is almost always the smarter bet. It's the central calculation everyone has to make during open enrollment.
What Actuarial Value Doesn't Tell You
Actuarial value is a fantastic starting point. It gives you a quick, at-a-glance idea of how generous a plan is supposed to be—the expected split between what the insurer pays versus what you pay. But if you stop there, you could be in for some nasty surprises. Think of it as just one piece of a much larger puzzle.
The most important thing to burn into your memory is that AV is an average, not a personal guarantee. It’s calculated based on how a "standard" population might use healthcare services over a year. Your own health, your medical needs, and how you actually use your plan will determine your real costs, which can look very different from that single percentage.
It Says Nothing About Your Doctors
A plan’s actuarial value has absolutely zero to say about its provider network. You could be comparing two Gold plans, both with an 80% AV, but one includes your trusted family doctor and the only hospital in your town, while the other doesn't.
Picking a plan without checking the network is one of the biggest and most expensive mistakes you can make. If you see an out-of-network doctor, your insurance might pay very little—or nothing at all. You get stuck with the entire bill. The metal tier means nothing if your doctors aren't in the plan.
It Overlooks Specific Drug Coverage
In the same way, actuarial value is completely silent on the plan’s formulary, which is just the official list of prescription drugs it covers. A Platinum plan with a high AV might seem like a sure bet, but what if it doesn't cover your essential daily medication? Or what if it puts that drug in a high-cost specialty tier?
You could be forced to pay a huge chunk of that medication's cost out-of-pocket. Always, always check that your specific prescriptions are on the formulary before you sign up. For anyone managing a chronic condition, this detail is everything.
An 80% AV plan that doesn’t cover your doctors or medications is far less valuable to you than a 70% AV plan that does. The numbers on paper are only a guide; the real value is in the details of the coverage.
It Doesn't Define Your Exact Costs
While AV gives you a general sense of the cost-sharing, it doesn't spell out how you'll pay your share. Two plans in the exact same metal tier can be structured in completely different ways.
For example, let's look at two Silver plans:
- Plan A: Has a low $2,000 deductible but you pay higher copays for every single doctor visit.
- Plan B: Comes with a high $6,000 deductible, but your costs are much lower once you've hit it.
Both plans can have a 70% AV, but they’re built for completely different people. Plan A is probably better for someone who sees their doctor frequently for predictable needs. Plan B is more for the person who wants solid protection against a major, unexpected health catastrophe.
You have to look past the AV percentage and dig into the nuts and bolts—the deductible, copays, and coinsurance. To get a better handle on these terms, you can read our guide on what coinsurance is in health insurance.
Choosing The Right Health Plan Using Actuarial Value
Alright, you've got the numbers down. Now it’s time to turn that knowledge into a real-world decision you can feel good about. Using actuarial value as your compass, you can build a simple framework to find a health plan that actually fits your life, moving you from theory to one of the most important financial choices you'll make all year.
The whole process starts with an honest look at your personal healthcare needs—and those of your family. Do you have chronic conditions that mean regular doctor visits or prescriptions? Are you anticipating a major medical event in the next year? Or are you generally healthy and just need a safety net for the unexpected?
Answering these questions is the key to picking the right metal tier. A young person with no major health concerns might be perfectly happy with a Bronze plan's low premium. On the other hand, a family managing diabetes will likely find the predictable costs of a Gold plan to be a much better fit.
Balancing Your Budget And Your Needs
Once you have a handle on your likely health needs, the next step is building a realistic budget. This goes way beyond just figuring out what you can afford for the monthly premium. You also have to ask yourself what you could comfortably pay out-of-pocket if a medical emergency struck tomorrow. A low premium looks great on paper, but a massive deductible can be a financial nightmare if you aren't prepared for it.
Your ideal health plan lives at the intersection of what you can afford monthly and the financial safety net you need. Actuarial value helps you find that sweet spot by clarifying the trade-off between premiums and out-of-pocket costs.
A great place to start is by checking if you qualify for subsidies. You can get a clear breakdown of how much you might save by learning about the health insurance premium tax credit. These credits can dramatically lower your monthly payments, opening up more plan options.
Moving Beyond The Metal Tiers
After you've used the metal tiers to narrow down your choices, it's time to get into the nitty-gritty details. Remember, actuarial value is an excellent guide, but it doesn't paint the whole picture. This is where you need to verify the specifics that will impact your day-to-day life.
Follow these steps to make sure a plan truly works for you:
- Check the Provider Network: Is your family doctor in-network? What about the local hospital or any specialists you see? Confirming this upfront is the best way to avoid surprise bills.
- Review the Drug Formulary: If you take any essential medications, make sure they are covered on the plan's list of approved drugs and find out what your copay will be.
- Compare Plan Structures: Look at the actual dollar amounts for deductibles, copays, and coinsurance. This tells you exactly how your costs are structured.
- Consider Modern Care Options: See how the plan covers things like convenient telehealth services, as this can affect your access to care and your overall spending.
Taking these extra steps ensures you're choosing a plan based not just on its "generosity score," but on how well it functions for your unique circumstances. A local expert at Pounds Health Insurance can walk you through this process, helping you compare plans side-by-side to find that perfect match.
Frequently Asked Questions About Actuarial Value
Health insurance can feel like a maze of confusing terms. Let's clear up some of the most common questions about actuarial value so you can feel confident when you're shopping for a plan.
Can Two Plans in The Same Metal Tier Have Different Costs?
Yes, and this is a really important point to understand. Actuarial value is just an average. Think of it as a guideline, not a strict rulebook for how a plan is built.
This means you could be looking at two Silver plans, both with a 70% AV, but they could feel completely different in practice. One might have a lower deductible but higher copays every time you see a doctor. The other could flip that around, with a steep deductible but better coverage once you meet it. You have to dig into the details of each plan’s Summary of Benefits and Coverage to see the real story.
Does Actuarial Value Include My Monthly Premium?
Nope. This is probably the single most common point of confusion. Actuarial value only looks at how the insurance company and you will split the bill for your covered medical expenses.
Your monthly premium is a completely separate cost you pay just to keep your insurance active. Your total healthcare spending for the year will be your monthly premiums added to all your out-of-pocket costs (deductibles, copays, and coinsurance).
What Are Cost-Sharing Reductions and How Do They Work?
Cost-Sharing Reductions, or CSRs, are a fantastic "extra savings" benefit. They are only available if you buy a Silver plan through the ACA Marketplace and your income falls within a specific range.
If you qualify, a CSR essentially boosts the actuarial value of your plan without making your premium go up.
For example, a standard Silver plan with a 70% AV might get supercharged into a plan with an 87% or even 94% AV. You get the high-end coverage of a Gold or Platinum plan but keep paying the lower Silver plan premium. It's an incredible deal for those who are eligible.
Is a Higher Actuarial Value Always Better?
Not always. The "best" plan for you really comes down to your health and your budget. A Platinum plan has a high AV, but it also comes with a hefty monthly premium.
If you're young, healthy, and don't expect to need much more than an annual check-up, you could end up paying a fortune in premiums for benefits you never touch. In that case, a Bronze or Silver plan with a lower premium might make more financial sense. It’s all about finding that sweet spot between a premium you can afford and the protection you need if something unexpected happens.
Trying to find that perfect balance can feel overwhelming, but you don't have to figure it all out on your own. The licensed agents at Pounds Health Insurance live and breathe this stuff. We're experts at cutting through the jargon to help you compare plans, see if you qualify for subsidies, and find coverage that fits your life.
For a free, no-pressure chat about your options, just visit us at https://poundshealthinsurance.com.











