Trying to shop for health insurance without a good comparison tool is like navigating a maze blindfolded. You're faced with endless options, confusing terms, and the nagging feeling you might be making a costly mistake. These tools are designed to be your guide, turning a confusing mess of data into clear, actionable choices that fit your life.
Why a Comparison Tool Is Your Best First Step
Not long ago, picking a health plan meant juggling paper brochures and spending hours on the phone. It was a frustrating, inefficient process. Thankfully, modern health insurance plan comparison tools have completely changed the game, acting as a powerful filter to help you zero in on the right coverage without all the noise.
Using one of these platforms is the smartest move you can make to protect both your health and your wallet. Whether you’re shopping for yourself, your family, or your small business, they provide the clarity you need to choose with confidence.
Cut Through the Clutter of Options
It's easy to feel overwhelmed. Whether you're trying to find health insurance or compare options for any other major decision, seeing everything laid out side-by-side is a game-changer. The U.S. Health & Medical Insurance market is enormous, with over 1,132 different companies all competing for your business. It's no wonder people get stuck.
A good comparison tool brings order to that chaos. Instead of opening a dozen browser tabs and trying to remember which plan had which feature, you get a single, organized view.
A smart comparison doesn't just make things easier—it can save you a surprising amount of money. We've seen clients save 20-30% on premiums each year simply by finding a plan that truly aligns with their health needs and budget.
For example, a tool instantly shows you how a plan with a low monthly premium might hide a sky-high deductible. Seeing that trade-off upfront is critical before you sign on the dotted line. To learn more about these trade-offs, you can dive deeper into our guide on https://poundshealthinsurance.com/how-to-compare-health-insurance-plans/ for more detailed strategies.
See Personalized Results Instantly
These tools aren't just simple lists; they create a customized shopping experience just for you. By plugging in basic information like your age, zip code, and estimated income, the tool immediately filters out plans you aren't even eligible for.
Here’s a perfect example of what that starting point looks like on a platform like HealthCare.gov.
This simple search is your gateway to a tailored list of options, often complete with estimated monthly costs and any subsidies you might qualify for. It takes a sea of thousands of national plans and shrinks it down to a manageable list that's actually relevant to you. That level of personalization is precisely what makes a health insurance plan comparison tool so incredibly effective.
Gathering Your Information for an Accurate Comparison
Any online health insurance comparison tool is really just a calculator. The answers it gives you are only as accurate as the numbers and details you feed into it. I’ve seen it a hundred times: someone rushes through this part and ends up with a plan that looks great on paper but falls apart in the real world.
Let's avoid that. Taking just a few minutes to gather the right details first will make the whole process faster and, more importantly, will give you a truly accurate picture of your best options. This isn't just about filling out forms; it's about making the tool work for you.
Your Household and Income Details
First, let's get the basics down for everyone in your household who needs coverage. You'll want their full names, dates of birth, and your home zip code, since plan availability is hyperlocal.
The most important piece of this puzzle, though, is your best estimate of your total household income for the upcoming plan year. Don't just pull a number out of thin air—this is the key that can unlock major savings.
Why is this so crucial? Your estimated income is what the system uses to see if you qualify for Advanced Premium Tax Credits (APTCs) to lower your monthly bill, or Cost-Sharing Reductions (CSRs) to reduce what you pay for actual medical care. These subsidies can be a game-changer, often saving a family thousands of dollars a year.
An inaccurate income estimate can mean you either miss out on savings you’re entitled to or get a nasty surprise when you file your taxes. The best way to get a solid number is to look at your most recent tax return and adjust it based on any expected changes for next year.
Your Healthcare Non-Negotiables
Now for the part that really personalizes your search. A plan with a $0 premium is useless if your trusted doctor isn't in its network or your essential medication isn't covered. We need to create a list of your family’s healthcare must-haves.
This is where you go from just "shopping for insurance" to finding the right health plan. Your list should cover three critical areas:
- Your Doctors and Hospitals: Who is your primary care doctor? What about your kids' pediatrician or your preferred cardiologist? Make a list of every single provider and facility you can't live without. Checking if they're in-network is non-negotiable for avoiding staggering out-of-network costs.
- Prescription Medications: Write down the exact name and dosage for every single prescription anyone in your family takes regularly. One plan might cover a drug with a simple copay, while another might not cover it at all, forcing you to pay hundreds out-of-pocket.
- Anticipated Medical Needs: Think about the year ahead. Are you expecting a baby? Planning a knee replacement? Is someone managing a chronic condition like asthma or diabetes? These big-ticket items will heavily influence whether a plan with a lower deductible or a lower maximum out-of-pocket is better for you.
Getting this information ready beforehand is the single best thing you can do to avoid the most common pitfall: choosing a plan on price alone. To get a deeper dive into making sure your providers are covered, our guide on how to verify insurance coverage walks you through that process step-by-step. A little prep work here ensures the plan you choose actually works for your life.
Making Sense of the Money: What the Key Numbers Really Mean
Alright, you've plugged your info into a health insurance plan comparison tool, and now you're staring at a screen packed with numbers and insurance jargon. It’s easy to feel overwhelmed, but don't sweat it. To get a real handle on the costs, you only need to focus on four key figures: the premium, the deductible, copays/coinsurance, and the out-of-pocket maximum.
This is where you move beyond the sticker price. A plan with the lowest monthly bill isn't automatically the best deal, and a pricey one isn't always a waste of money. The "right" plan for you depends entirely on how these numbers work together with your own health situation.
The Premium vs. Deductible Balancing Act
At the heart of every health plan is a trade-off between your fixed monthly cost and how much you pay before your insurance really starts helping.
- The premium is what you pay every month to keep your plan active. It’s a fixed, predictable bill, whether you go to the doctor 10 times or not at all.
- The deductible is the amount you have to pay out-of-pocket for your care before your insurance plan begins to pay its share.
Let’s put this into a real-world context. A young, healthy graphic designer might lean toward a plan with a low $150 monthly premium. The catch? It comes with a high $8,000 deductible. They're essentially betting on staying healthy, keeping their monthly expenses super low while accepting the risk of a big bill if something unexpected—like a major accident—happens.
Copays and Coinsurance: Your Share of the Bill
Hitting your deductible doesn't mean you're done paying. That's when copayments (copays) and coinsurance enter the picture.
- Copays: These are simple, flat fees for a specific service. You might pay $35 for a check-up with your primary care doctor or $75 to see a specialist.
- Coinsurance: This is a percentage you split with your insurer. If your plan has 20% coinsurance for a hospital stay and the bill is $10,000, you’d owe $2,000 (assuming your deductible is already paid).
Now, flip the scenario. Think about someone managing a chronic condition like diabetes. For them, a plan with a higher $500 monthly premium but a low $1,500 deductible is often the smarter financial move. They know they’ll have regular appointments and prescriptions. Paying more each month means their insurance kicks in much sooner, potentially saving them thousands over the course of the year.
I always tell my clients to stop looking for the "cheapest" plan and start looking for the most "cost-effective" one. The goal is to balance the fixed monthly premium with your realistic, anticipated healthcare usage for the year. That's the secret to finding true value.
The Out-of-Pocket Maximum: Your Financial Safety Net
This number is arguably one of the most important on the page. The out-of-pocket maximum is the absolute most you will have to pay for covered medical services in a year.
It’s your ultimate financial protection. Once you hit this limit by paying your deductible, copays, and coinsurance, your insurance company covers 100% of all covered costs for the rest of the plan year. No more bills.
These online tools have been a game-changer for millions. ACA marketplace enrollment hit a record 21.3 million in 2024, partly because these platforms make it easier to see your options. In fact, they helped 65% of enrollees find Silver plans with valuable cost-sharing reductions. With users switching plans 40% more efficiently and saving an average of $1,200 per family, the impact is undeniable.
This process works by taking your personal information and running it through the plan's cost structure, as this flowchart shows.
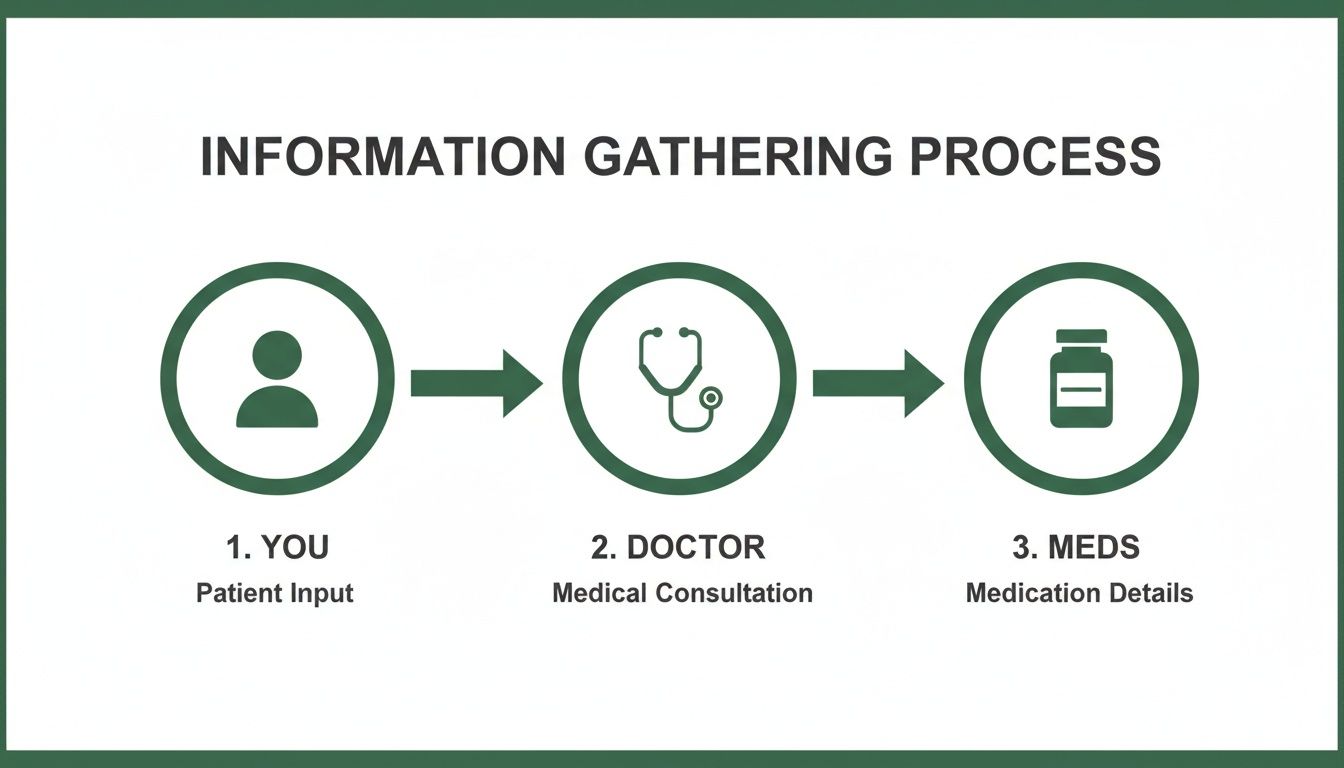
As you can see, your specific doctors, medications, and health needs are what allow the tool to generate those personalized cost estimates. For a deeper dive into how these costs relate to a plan’s overall generosity, check out our guide on what is actuarial value in health insurance.
By looking at these numbers together, a health insurance plan comparison tool helps you forecast your total potential spending. It empowers you to make a choice that protects both your health and your finances.
Look Beyond the Price Tag: Check Your Doctors and Prescriptions
A plan with a low monthly premium is tempting, I get it. But it can be a classic bait-and-switch if it doesn't cover the doctors you see and the medications you rely on. Once you've sorted through the main costs, your next move is to dig into two things that truly define a plan's value: its provider network and drug formulary.
Honestly, these are the factors that separate a good plan from a year of frustration and surprise bills. They answer the two questions that matter most: "Can I keep my doctor?" and "Will my prescriptions be affordable?"
Make Sure Your Doctor is In-Network
A provider network is simply the list of doctors, hospitals, and specialists that have a contract with your insurance company. Staying inside that network is the best way to keep your costs down, period. A good health insurance plan comparison tool will let you search for your specific doctors right on the results page.
When you do, you'll run into a few common network types:
- HMO (Health Maintenance Organization): These plans usually offer lower premiums, but you have to stick to their list of providers. You’ll also typically need a referral from your primary care physician (PCP) to see any specialists.
- PPO (Preferred Provider Organization): PPOs give you the freedom to see doctors both in and out of the network, often without a referral. That flexibility usually comes with a higher monthly premium.
- EPO (Exclusive Provider Organization): Think of this as a hybrid. Like an HMO, it only covers in-network care (except for emergencies). But like a PPO, it often doesn't require referrals for specialists.
People really value this flexibility. In North America, which makes up a 62.1% share of the global health insurance market, PPOs are incredibly popular for this reason. This isn't just for younger people, either; seniors are a huge part of this trend. By 2026, enrollment in comparable Medicare Advantage plans is expected to hit 33 million. If you're interested in the wider market trends, you can discover more insights about the global health insurance market from Research and Markets.
Search the Drug List (Formulary)
Just as critical is the plan’s drug formulary—the official list of prescriptions it covers. Any worthwhile health insurance plan comparison tool has a feature where you can type in your specific medications to see how each plan handles them. Don't skip this step.
Formularies use "tiers" to sort drugs by cost:
- Tier 1: Your cheapest options, mostly common generic drugs.
- Tier 2: Preferred brand-name drugs, which come with a higher copay.
- Tier 3 & 4: Non-preferred brand-name drugs and specialty medications. These are your most expensive prescriptions.
My Biggest Piece of Advice: Never, ever assume a medication is covered. Use the tool's search feature every single time. A plan that looks like a bargain can quickly become a financial nightmare if one of your essential drugs isn't covered or is stuck in a high-cost tier.
Here's a real-world example. Imagine a family with a child who needs a specific asthma inhaler that costs $300 out-of-pocket.
- Plan A has a low premium, but it puts the inhaler in Tier 3, meaning the family pays 50% of the cost ($150) every month.
- Plan B has a higher premium but lists that same inhaler as a Tier 2 drug with a flat $40 copay.
By looking past the premium, the family would realize Plan B saves them more than $1,300 a year on that one medication alone. That’s the kind of vital information these tools are built to uncover. To get a better handle on how all this works, our guide on what is a provider network offers a much deeper dive.
From Top Contenders to Your Final Choice
You’ve done the heavy lifting. After running the numbers through a health insurance plan comparison tool, you’ve likely whittled down thousands of plans to just two or three strong contenders. This is where you switch gears from data-crunching to making a real-world decision for your family.
It's time for one last, focused review. Pull up your top two or three plans and think through how each one would actually play out. Forget the spreadsheet for a moment and consider the practical side of things.
For instance, Plan A’s low premium is tempting, but does its smaller network mean you'd have to switch your trusted family doctor? Plan B might cost a little more each month, but it covers your son's specific allergy medication with a simple copay and includes that great pediatric hospital network. This is about your life, not just the numbers.
Avoid Common Decision-Making Traps
At this final stage, it's incredibly common to get hung up on a single number. I've seen countless people fixate on finding the absolute lowest premium, only to later discover the plan has terrible customer service ratings or a history of denying claims.
A good health insurance plan comparison tool might show you some of this information, but it can’t weigh it for you.
A plan is so much more than its costs and benefits. It’s a service you rely on when you're sick or hurt. An insurer’s reputation for paying claims without a fight is just as critical as its price tag.
Get an Expert Second Opinion
This is the perfect time to bring in a human expert to double-check your work. Think of us at Pounds Health Insurance as a sounding board—someone who can validate your research and spot things a comparison tool might have missed. We do this every day, so we know exactly what to look for.
A quick chat with an experienced agent can make all the difference. We can:
- Confirm Your Subsidies: We’ll make sure your income is calculated correctly so you get every dollar in tax credits or cost-sharing reductions you qualify for. It’s easy to leave money on the table here.
- Spot Potential Gaps: You might love a plan's low deductible, but we might notice its prescription coverage for a specific condition is weak. We look at the whole picture.
- Validate Your Finalists: We can give you an honest take on whether your top choice is truly the most practical and cost-effective option for the year ahead.
This final check-in doesn't undo the great research you've done; it strengthens it. It gives you that last piece of confidence before you commit.
When you’re set, our guide on how to enroll in health insurance will walk you through the last few clicks. With a choice backed by both solid data and expert advice, you're ready to enroll and feel good about it.
Common Questions We Hear About Plan Comparison Tools
Once you start digging into these comparison tools, a few questions inevitably pop up. It’s completely normal. We hear them from clients all the time, so let's tackle some of the most common ones right now.
When’s the Right Time to Start Comparing Plans?
Most people think of health insurance shopping as a once-a-year event, and they're mostly right. The main window is the annual Open Enrollment Period, which in most states runs from November 1st to January 15th. During this time, anyone can shop for and enroll in a new plan.
But what if you need coverage outside that window? You might be in luck if you've had a Qualifying Life Event (QLE). These are significant life changes that open up a Special Enrollment Period just for you.
You might have a QLE if you:
- Get married or divorced
- Have a baby or adopt a child
- Lose health coverage from a job
- Move to a different zip code with new plan options
If any of these sound like your situation, it's a good idea to chat with a licensed agent. We can quickly verify if you qualify and walk you through the process.
Can I Use These Tools for My Small Business?
Yes, but it's a different ballgame. The comparison tools you see online are typically built for individuals and families shopping on the ACA Marketplace. They aren't designed to handle the complexities of group health insurance.
For small businesses, we use specialized software that isn't available to the public. This allows us to analyze quotes from multiple carriers and build a benefits package that makes sense for your company's budget and your employees' needs. It's a tricky balance to strike on your own, but it's exactly what we do day in and day out.
Are the Prices I See on the Tool Guaranteed?
This is a great question. Think of the prices you see on a health insurance plan comparison tool as highly accurate estimates. They’re based entirely on the information you provide.
The final, official premium and subsidy amount are only locked in after the Health Insurance Marketplace or the insurance carrier has processed and verified your complete application.
This is precisely why getting the application right the first time is so critical. An agent can double-check that all your information is correct, helping you avoid any last-minute surprises and ensuring you get the lowest possible rate you're entitled to.
What Happens If I Accidentally Pick the Wrong Plan?
This is probably the most important question of all, because getting it wrong can be a real headache. Once you enroll, you’re generally locked into that plan for the rest of the year.
You can't just switch to a different plan mid-year unless you experience another Qualifying Life Event. This is why it’s so crucial to be thorough during your initial comparison. Making a mistake could mean being stuck with a plan that doesn’t cover your doctors or has costs that strain your budget. The best way to prevent this is to get a second opinion from an expert before you finalize your decision.
Ready to move from comparing plans to confidently enrolling in the right one? The experienced agents at Pounds Health Insurance are here to provide a free consultation, answer all your questions, and ensure you find the perfect coverage. Visit us at https://poundshealthinsurance.com to get your fast, no-pressure quote today.