Employer-sponsored family coverage averaged $26,993 in total annual premiums in 2025, and covered workers contributed about $6,850 of that themselves. On the Marketplace, tax credits can shrink the lowest-cost plan to a projected $50 a month for eligible enrollees. Below, we show how to estimate your own number.
TL;DR:
- Ask HR for the family tier deduction, then compare deductibles and copays, because a low payroll cost can conceal higher bills when care is needed.
- Marketplace credits depend on estimated income and household size; report changes promptly, since failing to update them can leave you owing money at tax time.
- With a chronic condition or planned procedure, compare premiums plus expected care costs; Bronze and Silver shift more spending to you when care is needed.
- Price family coverage against separate plans when adults and children qualify for different subsidies, since split policies create separate deductibles and out of pocket limits.
- Check prices and provider networks by county, not just national averages, because insurer choices and local medical costs vary across states and regions.
Table of Contents
- What do average family premiums look like right now?
- How does employer coverage change what your family actually pays?
- How do Marketplace subsidies change monthly costs?
- Which plan level and cost drivers should you compare?
- How can you estimate your family’s monthly premium?
- Why does your state change the price?
- What are the best ways to lower premiums and total costs?
- Is family coverage cheaper than individual plans for each member?
- Why we recommend a personalized comparison
- Get a personalized family plan quote from Pounds Health Insurance
- FAQ
- Sources
What do average family premiums look like right now?
Start with the national picture, because it tells you whether a quote is normal or a red flag. The 2025 KFF Employer Health Benefits Survey puts the total annual employer-sponsored family premium at $26,993. That total is the full price of the plan, not what your paycheck loses.
A few figures worth keeping in mind:
- Total family premiums have risen 26% over the past five years.
- Workers pay about 26% of the total family premium on average, which works out to $6,850 a year.
- The Bureau of Labor Statistics reports a median annual premium of $6,996 for family coverage among civilian workers, a useful second lens on what workers carry.
The two numbers answer different questions. One is the sticker price of the plan. The other is the slice that comes out of a typical worker’s pay. When you compare offers, line up the same measure on both sides.
How does employer coverage change what your family actually pays?
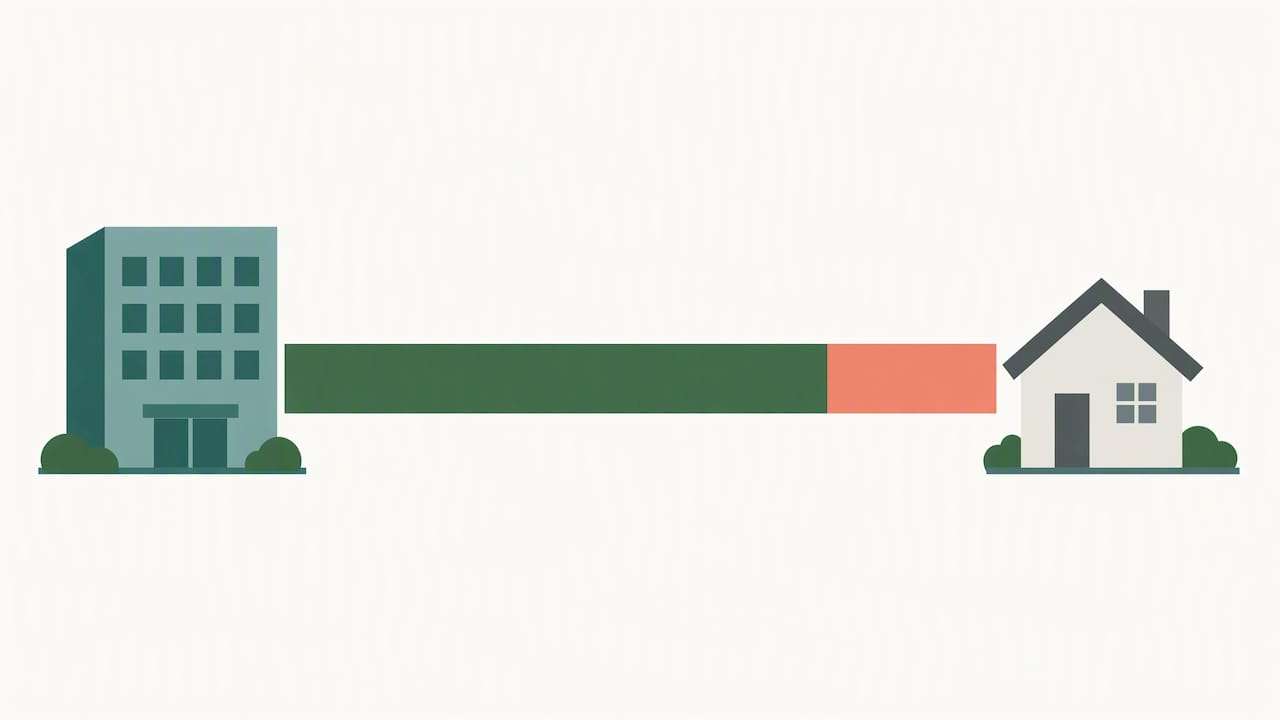
Most families on a job-based plan never see the $26,993. Employers cover most of it, and you see only your payroll deduction. Still, that deduction is real money. KFF health policy experts note that the total cost of a family plan can exceed 40% of a typical full-time worker’s earnings, which is why the employer’s share matters so much.
Here is how to read an offer from your employer:
- Payroll deduction: this is your share of the premium, and it lowers your take-home pay every pay period.
- Deductible and copays: these come on top of the premium, so a low deduction can hide a high deductible.
- Firm size: BLS data shows the share paid by workers in small establishments is higher than in large ones, so a small employer may pass along more cost.
Ask HR for the family-tier deduction, not just the employee-only number. Families often get surprised there.
How do Marketplace subsidies change monthly costs?
If you buy through the Marketplace, the premium tax credit can change the math more than any other factor. The size of the credit depends on household size and estimated income. You can take it monthly in advance, or claim it when you file taxes.
The 2026 picture: CMS projects the average monthly premium after tax credits for the lowest-cost plan among eligible enrollees at $50, with credits covering roughly 91% of that premium on average.
A few practical points:
- Nearly 60% of eligible re-enrollees will have access to a plan at or below $50 a month after subsidies, per the same CMS fact sheet.
- Credits are sensitive to income and family size, so a raise or a new baby can move your number.
- If your income or household changes, report it to the Marketplace. Skipping that step can mean owing back credits at tax time.
These are averages for eligible enrollees. Your own credit could be higher or lower.
Which plan level and cost drivers should you compare?
A low premium is not the same as a low cost. HealthCare.gov sorts plans into four metal categories: Bronze, Silver, Gold and Platinum. They describe how you and the plan split costs, not how good the care is.
- Bronze and Silver: lower monthly premiums, with more of the bill falling to you when care is needed.
- Gold and Platinum: higher premiums, with less out of pocket when you use care.
- Other drivers: deductible, copays and coinsurance, network breadth, family size and how much care you expect to use.
Pro Tip: If someone in your household has a chronic condition or a planned procedure, price the whole year, premiums plus likely care, before you choose the lowest monthly bill.
How can you estimate your family’s monthly premium?
You do not need a spreadsheet. Work through these steps in order:
- List every household member and estimate your income for the calendar year, since Marketplace eligibility uses estimated income.
- Check whether you have an employer offer. If you do, find the family-tier deduction and the network. If not, move to the Marketplace.
- Pick a metal level, then browse prices with the official See Plans & Prices tool or request insurer quotes.
A quick worked example, with illustrative figures only: a family finds a Silver plan priced at a certain amount before credits, and their tax credit covers part of that cost. Their monthly bill is the premium minus the credit. Change the income estimate and that credit moves, which is why Step 1 matters most.
Keep these in mind too:
- Families do not have to enroll everyone on the same plan, and household and tax-filing details decide who qualifies for credits.
Why does your state change the price?
Premiums are not set nationally. Insurer pricing, local medical costs and competition all push state averages above or below the national figure. The BLS medical care premiums report shows how much costs vary across employers, and the same logic applies across regions.
What this means for you:
- Do not budget from a national average alone. Check your state’s Marketplace page for local plan prices.
- Look at several carriers, because prices and networks differ county by county.
- If you move, treat it as a fresh shopping event, since your plan options may change.
What are the best ways to lower premiums and total costs?
Rank these by impact, and start at the top:
- Use premium tax credits, and cost-sharing reductions when you qualify. Report income and household changes promptly.
- Compare metal levels, and confirm your essential doctors are in network before you enroll.
- Ask HR what your employer contributes, and whether a spouse’s plan costs less.
- Consider child-only plans when they are cheaper, knowing children then carry separate deductibles and out-of-pocket maximums.
- Add supplemental coverage if you face recurring, predictable costs.
Pro Tip: Small changes to your income estimate or household filing can change your credit a lot, so plan before you enroll rather than after.
Is family coverage cheaper than individual plans for each member?
Often, but not always. A family policy can bundle everyone under a shared deductible and out-of-pocket maximum, and it usually keeps paperwork simple. Separate individual plans can make sense in specific situations.
Family coverage tends to win when:
- Your household shares one employer offer or one Marketplace application.
- You want one deductible that every member’s care counts toward.
Separate plans can win when:
- Adults and children qualify for different help. Families do not have to enroll all members on the same plan, and household and tax details decide who gets credits.
- A child-only plan costs less than adding the child to a parent’s policy.
The tradeoff is structural. Split plans mean separate deductibles and out-of-pocket maximums, so a bad year for multiple people can cost more than one family plan would have. The only reliable test is to price both ways for your exact household. We can run both versions side by side, and you can also read our guide to the best plans for families. If you are an employer weighing plan design for your workers, this PPO vs HDHP comparison shows how plan choice affects costs.
Why we recommend a personalized comparison
Averages are a starting line, not a quote. In our experience, the families who feel least stressed about coverage are the ones who saw real numbers for their own income and household before they chose. As an independent agency, we compare plans across multiple carriers, so you are not looking at one company’s version of the answer. We also walk families through how tax credits work and how plan design shifts total costs, then run quotes for your household and help with Marketplace enrollment or evaluating an employer offer. If you want a number you can trust, ask us for a tailored quote. Our family health insurance quotes guide is a good first read.
— Pounds Health Insurance
Get a personalized family plan quote from Pounds Health Insurance

You should not have to decode premiums, credits and metal levels alone. We compare plans from several carriers, help you understand your subsidy, and match coverage to your budget and the care your family actually uses. There is no pressure, just clear options. Tell us your household size and income, and we will show you what coverage could cost. Visit our family health plans page to request a quote today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How much is health insurance for a family of four in the USA?
It depends on how you get coverage. Employer-sponsored family plans carried an average total premium of $26,993 a year in 2025, though workers pay only a share of that. Marketplace families may pay far less after tax credits.
Is the average cost of a family health insurance plan now $27,000?
For employer-sponsored coverage, the total is close to that. KFF puts it at $26,993 in 2025, but employers pay most of it, and the average worker contribution is about $6,850.
Is $500 a month normal for health insurance?
For a family, it can be, depending on your plan and income. Employer deductions and Marketplace prices vary widely, so compare your number against your family-tier deduction or your subsidized Marketplace price.
What state has the cheapest health insurance?
It changes by year and by plan type, and we cannot point to one state without a current source. Premiums depend on local medical costs and insurer competition, so check your state’s Marketplace page for current prices.
Sources
- Kff
- Plan Year 2026 Marketplace Plans and Prices Fact Sheet | CMS
- Healthcare
- Medical care premiums in the United States : U.S. Bureau of Labor Statistics