
When you start searching for "independent health insurance agents near me," you're taking the most important first step toward navigating the maze of healthcare coverage. Unlike an agent who works for just one company, an independent agent is on your team. They have access to a wide range of plans and can help you find the right one for your family and your wallet. This single difference is the key to unlocking better coverage and more confident choices.
Why An Independent Agent Is Your Best Ally
The world of health insurance can feel like a tangled mess. When you start looking, you'll run into two kinds of professionals: captive agents and independent agents. Knowing how they differ is crucial before you even think about comparing plans.
A captive agent is employed by a single insurance company. Their job is to sell you products from that one carrier, even if another company has a plan that would be a much better fit for you. Their loyalty lies with their employer, not you, which can seriously limit your options.
An independent agent, on the other hand, is your personal advocate in the insurance market. They aren't tied to any one carrier. Instead, they build relationships with multiple insurance companies, giving them the freedom to truly shop around for your benefit.
The Power Of Choice And Unbiased Advice
This independence is a huge advantage for you. An agent who can pull quotes from Aetna, Cigna, UnitedHealthcare, and other local carriers has a bird's-eye view of everything available. Their recommendations aren't biased by a sales quota from a single brand; they're based entirely on what makes sense for your life.
This becomes especially valuable when you have specific needs:
- ACA Marketplace Plans: They can quickly see if you qualify for tax credits (subsidies) to lower your premium and help you through the sometimes-tricky application.
- Self-Employed Coverage: They know the hurdles freelancers and small business owners face and can find plans with the right doctor network and a deductible you can actually afford.
- Small Group Benefits: For business owners, they can design a competitive benefits package by mixing and matching the best offerings from several different carriers.
An independent agent’s expertise also goes beyond just the plans themselves, often including a deep understanding of how the industry works, from claims processing to the strategic outsourcing of insurance processes.
An independent agent acts as a personal shopper, a translator for confusing insurance jargon, and a long-term partner for your healthcare journey. Their goal is to simplify everything, not just to sell you a policy.
At the end of the day, working with independent health insurance agents near you gives you a dedicated expert who is committed to your best interests. They take the time to understand your family’s medical history, budget, and which doctors you want to keep. You can learn more about what we do in our article on what a health insurance broker does. Having this foundation ensures the decision you make is informed, confident, and the right one for you.
How to Zero In on the Best Local Agents
Starting the hunt for an "independent health insurance agent near me" can feel like shouting into the void. But with the right strategy, you can quickly move past the generic results and build a shortlist of real pros who know their stuff. This isn't just about finding a salesperson; it's about finding a guide.
The whole point is to connect with someone who truly understands the local healthcare scene. They know which plans work with which hospital systems and can steer you away from a policy that looks great on paper but falls apart in the real world—your world.
Get Specific With Your Online Search
To find the right people, you have to ask Google the right questions. Generic searches will get you generic results, often from massive national call centers. Instead, think about your specific situation and bake those details right into your search query.
Try search phrases that get straight to the point:
- "ACA certified agent for freelancers in Tampa"
- "Independent health insurance broker for small business St. Petersburg"
- "Family health insurance advisor Sarasota FL"
- "Agent specializing in self-employed health plans near me"
See the difference? These targeted searches help you find agents with hands-on experience in your exact situation. Adding your city or county is non-negotiable for finding someone with that crucial local knowledge. You can dig deeper into this topic in our guide to finding health insurance brokers near you.
Use Professional Directories to Vet Your Options
A smart Google search is a great first step, but don't stop there. Professional directories and government resources add a much-needed layer of verification, helping you confirm you're dealing with a licensed, credible professional.
Your state's Department of Insurance website should be your first stop. Every state has one, and they almost always have a tool to look up an agent's license status and see if they have any disciplinary history. This is a must-do check.
Another excellent resource is the National Association of Benefits and Insurance Professionals (NABIP). Their online directory lets you find members in your area, which is a good sign—it shows the agent is invested in their profession and committed to staying on top of industry standards.
Tapping into these official resources is the best way to cut through the marketing fluff. It helps ensure the agents on your list are not only licensed but are actively engaged professionals, which usually means better expertise and service for you.
Create a Solid Shortlist
As you search, your goal should be to build an initial list of three to five promising agents. Don't just grab the first few names you see. Take a minute to click through to their websites. Do they have client testimonials? Do they clearly state what kind of insurance they specialize in—individual, family, or small business?
A good agent’s website will also be transparent about the insurance carriers they partner with, like Aetna, Cigna, or Blue Cross Blue Shield. That kind of upfront honesty is a great sign. By combining smart searches with trusted directories, you'll end up with a high-quality list of candidates, perfectly teeing you up for the next step: vetting them to find your perfect match.
You’ve got a shortlist of local independent agents. Great. Now comes the critical part: figuring out which one is a true expert who can actually help you.
This isn't about just picking the one with the best website. It's about doing a little homework to make sure they're qualified, well-connected, and genuinely equipped to find the right plan for your specific situation. Think of it as a final interview before you hand over one of the most important financial decisions for you or your family.
First things first, and this is non-negotiable: verify their license. Every legitimate agent must be licensed by the state. A quick search on your state's Department of Insurance website will tell you if their license is active and if they have any complaints or disciplinary actions against them. If you can't find them, that's a major red flag. Move on.
Confirm Their Carrier Appointments
An independent agent's superpower is choice. They aren't tied to one company, so they can shop the market for you. But here’s the catch: they can only sell plans from insurance carriers they are officially "appointed" with.
One agent might have appointments with five carriers, while another has fifteen. That difference is huge. If they aren't appointed with, say, Blue Cross or UnitedHealthcare, they literally cannot show you those options, even if they're the best fit for you.
So, ask them directly: "Can you send me a list of the insurance carriers you're appointed with?" A good, transparent agent will have this ready to go. This simple question instantly reveals the true scope of plans they can offer you.
This is exactly why the independent agency model is so powerful. It's no surprise that independent agents place 61.5% of all property and casualty insurance in the U.S. They dominate the market because they bring a level of choice and personalization that a single-carrier agent just can't. You can dig into more of this data in the latest market share findings from the Independent Insurance Agents & Brokers of America.
Verifying an agent’s carrier appointments is like checking a restaurant’s menu before you sit down. You want to make sure they have the ingredients (the insurance plans) to create the right meal (your health coverage) for you.
Match Their Experience To Your Situation
Health insurance isn't a one-size-fits-all product, and agents often develop specialties. The agent who’s a rockstar at setting up large corporate benefits plans might be completely out of their depth when it comes to helping a freelancer find a good ACA plan. You need someone who lives and breathes your world.
Be specific about what you need and see how they respond.
- Self-Employed or Freelancer? Ask them how many ACA/Marketplace plans they sold last year. Ask about their experience helping clients qualify for subsidies.
- Small Business Owner? Ask about their process for quoting small group plans and how they handle employee onboarding and questions. Do they have experience with level-funded plans?
- Looking for Family Coverage? Ask how they approach finding a plan that balances different needs—like one spouse needing a low deductible and the other needing robust prescription coverage.
Asking pointed questions like these will quickly tell you if they have the right kind of experience. You want someone who has already solved the problems you’re facing for dozens of other clients. This kind of specialized knowledge is invaluable, especially when it's time to dive into the nitty-gritty of a plan's documents. You can get a head start by learning how to read a plan's details in our guide on understanding a Summary of Benefits and Coverage.
Essential Questions To Ask Before Choosing Your Agent
You’ve done your research and have a short list of potential agents. Now for the most important part: the interview. This isn't just a casual chat; it's your chance to see how they operate, what their communication style is like, and if they genuinely have your best interests at heart.
Think of it this way: you’re not looking for a salesperson. You're looking for an advocate. The answers you get will quickly separate the professionals who are ready to dig into the nitty-gritty for you from those just looking to make a quick sale.
Questions About Their Process And Expertise
Let's start with questions that cut to the chase about how they actually work. You need to understand their strategy for finding the right plan for you, which goes way beyond just the monthly premium.
"How do you help clients compare plans beyond just the premium?" A true expert won't miss a beat. They should immediately start talking about things like deductibles, out-of-pocket maximums, doctor networks, and which prescriptions are covered. Their goal should be to show you the total potential cost over a year, not just the number on your monthly bill.
"What is your process for checking if my preferred doctors and prescriptions are covered?" Vague answers won't cut it here. A good agent will describe a clear, systematic process. They should be using the insurance company’s specific provider search tools and official drug lists to verify coverage, not just making an educated guess.
You can even draw inspiration from other fields when you're vetting an expert. For example, some of the essential questions to ask a web designer are surprisingly relevant, as both situations involve hiring a specialist for a complex and personal need.
Uncovering Their Client Support Philosophy
Alright, let's shift gears. What happens after you get your insurance card in the mail? A great agent’s job doesn't end there—in fact, that's often where the real work begins. This is a huge differentiator when you're comparing local agents.
Your goal is to find an agent who views the relationship as a long-term partnership. Ask questions that reveal their commitment to being your advocate when you need it most, such as during a claims issue or when it's time for renewal.
"What kind of support do you offer clients after the policy is active?" Listen for specifics. Do they mention helping with confusing claims, sorting out billing questions, or finding an in-network specialist? That’s the kind of hands-on support you want.
"How do you handle the renewal process each year?" A proactive agent will have a clear plan. They should describe how they'll touch base with you, re-evaluate your needs, and then shop the market again to make sure you're still in the best possible plan for the coming year.
More and more people are realizing how valuable this kind of personalized guidance is. In fact, the global healthcare insurance market sold through individual agents is projected to hit USD 1.14 trillion soon, with North America leading the way. That huge number shows just how many people are actively seeking the tailored advice that a good independent agent can provide.
Taking the time to ask these detailed questions ensures you find an agent who truly adds that value. For more on what to look for in a plan, our guide on how to compare health insurance plans is a great place to start.
It’s Decision Time: Choosing Your Plan and Getting Ready to Enroll
You've done the hard work of vetting agents and asking all the right questions. Now comes the final, most important part: picking the right plan and partner to guide you through enrollment. This is where you move beyond the agent's personality and dig into the nitty-gritty of the plans they've presented.
A great independent agent will have laid everything out for you, but the final say is yours. It's so easy to get fixated on the monthly premium, but that number rarely tells the whole story. A cheap plan might look great on paper, but if it comes with a deductible so high you can't afford to actually use it, what's the point?
How to Compare The Quotes Like a Pro
To feel truly confident in your choice, you need to put the core details of each plan side-by-side. Forget the marketing fluff and focus on the numbers that will directly impact your wallet and your health.
Here’s what I always tell my clients to zero in on:
- Deductibles & Out-of-Pocket Maximums: The deductible is what you pay first, before insurance really kicks in. The out-of-pocket maximum is your financial safety net—the absolute most you'll pay for covered services in a year. Make sure you can comfortably handle both.
- Provider Networks: This is non-negotiable. You must verify that your preferred doctors, specialists, and hospitals are in-network. Your agent should give you direct links to the insurance carrier's provider directory. Take the five minutes to search for your doctors by name. It’s a critical step.
- Prescription Drug Coverage: If you rely on specific medications, check the plan's formulary (its list of covered drugs). Find out what your copay will be. A plan that doesn’t cover your daily prescription can turn a good deal into a financial nightmare overnight.
This little diagram breaks down the final gut-check on an agent. It's all about making sure their expertise, the coverage they found, and their process all line up perfectly for you.
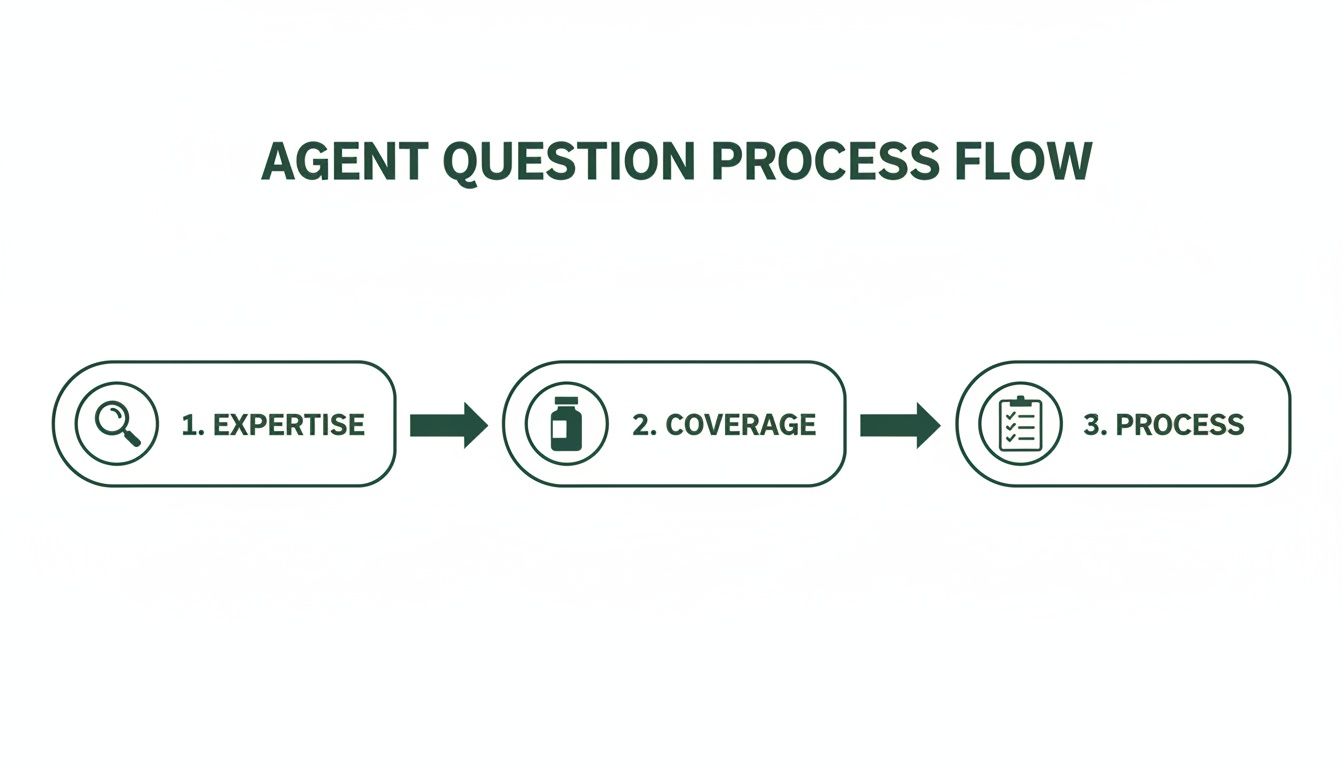
Ultimately, your decision comes down to confirming the agent has the right expertise, found coverage that truly fits your needs, and has a process you feel comfortable with.
Get Your Ducks in a Row for Enrollment
Once you've picked your agent and your plan, the actual application can be surprisingly fast—if you’re prepared. To get you the best possible plan, especially if you qualify for subsidies on the ACA Marketplace, your agent needs some specific information.
From my experience, having your documents ready beforehand is the single best thing you can do for a smooth, error-free enrollment. It lets your agent focus on submitting everything correctly and on time, without any last-minute scrambling.
Before your enrollment meeting, try to gather these items:
- Social Security numbers for every person in your household who needs coverage.
- Basic employer and income details, like recent pay stubs or a W-2.
- Your best guess for your total household income for the upcoming year.
The health insurance industry is enormous—it's projected to grow from USD 3.4 trillion to an almost unbelievable USD 6.6 trillion. A lot of that growth is being driven by people just like you who want flexible plans like PPOs. This just shows how vital an independent agent is for navigating the ever-growing sea of options. You can even discover more about health insurance market trends if you want to see the forces shaping the industry.
From that first phone call to the day your insurance cards arrive in the mail, a good agent makes a complicated world feel simple.
Common Questions About Working with an Independent Agent
It’s totally normal to have a few questions, even when you know an independent agent is the right call. Let's clear up some of the most common ones so you can move forward with confidence.
Probably the biggest question on everyone's mind is, "What's this going to cost me?" Here's the great news: you don't pay anything extra for an agent's help. Their services are completely free to you.
How does that work? Simple. The insurance carriers pay them a commission after you enroll in a plan. This means their fee is already baked into the premium price, whether you use an agent or not. So, you get an expert guide without an extra bill.
Do Independent Agents Help with ACA Marketplace Plans?
Yes, absolutely. In fact, navigating the Affordable Care Act (ACA) Marketplace is where a great independent agent really shines. They are certified experts who know the system inside and out.
One of the first things they’ll do is see if you qualify for premium tax credits (subsidies), which can slash your monthly premium. They'll walk you through the application, making sure your income is reported correctly to get you every dollar of savings you’re entitled to. Trying to figure this out alone can be a real headache, and mistakes can be costly.
Think of an independent agent as your personal translator for the ACA Marketplace. They turn confusing rules into clear choices and help you sidestep common pitfalls that could jeopardize your coverage or your savings.
What Kind of Support Can I Expect After Enrollment?
A good agent's job isn’t done when your ID cards arrive in the mail. They become your go-to resource for the life of your policy, which is a huge benefit of working with a local pro.
Here’s a taste of the ongoing support you can expect:
- Decoding Your Policy: Got a bill that looks like it's written in another language? Need to know if a specific procedure is covered? Your agent is the first person you should call.
- Fighting Your Battles: If a claim gets denied or tangled in red tape, your agent will get on the phone with the insurance company for you. They know who to talk to and how to get things resolved.
- Handling Renewals: When renewal season rolls around, they’ll be proactive. They'll review any changes to your current plan, check out the new options on the market, and make sure you're still in the best plan for the year ahead.
This long-term partnership gives you incredible peace of mind. For a deeper dive into the process, check out our guide on how to shop for health insurance.
Ready to find a health insurance plan that truly fits your life and budget? The team at Pounds Health Insurance is here to provide the clear, expert guidance you deserve. We shop all the major carriers to find the perfect coverage for you, your family, or your small business, with no pressure and no hidden fees. Get Your Free Quote Today!











